By Chuck Roulet, Attorney at Law, Roulet Law Firm, P.A.
On November 3, 2026, Florida voters approved Amendment 3 with about 62 percent of the vote. It needed 60 percent to pass. It is the largest change to Florida property taxes in decades.
For people who already live here, it's welcome news. For people who live somewhere else and are thinking about moving, it creates a hard deadline. If you are a permanent Florida resident on December 31, 2026, you can qualify for the full benefit. If you aren't, you may wait five years for it.
I'm an estate planning and elder law attorney licensed in both Florida and Minnesota. For nearly 30 years I've helped families plan their lives and their estates, and much of my work now is helping families make the move to Florida the right way. Here is what you need to know.
What Amendment 3 Changes
Before Amendment 3, a Florida homestead received an exemption of up to about $50,000 of assessed value. The first $25,000 applies to all property taxes, including school taxes. The second part applies only to non-school taxes.
Amendment 3 raises the non-school exemption. Starting with the 2027 tax year, the homestead exemption for non-school taxes is $150,000. Starting in 2028, it is $250,000, and it adjusts for inflation after that.
A few things stay the same. The school tax exemption remains $25,000. Special assessments, such as CDD fees and other non-ad valorem charges, are not reduced. Save Our Homes still limits how fast your homestead's assessed value can rise, to 3 percent or the rate of inflation, whichever is lower. Existing exemptions for seniors, veterans, and people with disabilities remain in place.
For non-homestead property, such as second homes, rentals, and commercial property, the annual cap on assessment increases for non-school taxes drops from 10 percent to 5 percent. That limits how fast the assessed value can grow. It is not a 5 percent cut in your tax bill.
None of this lowers your 2026 tax bill. The first effects show up on 2027 assessment notices and tax bills.
The Catch for New Residents
Amendment 3 creates two groups of homeowners. The dividing line is whether you maintained a permanent residence in Florida as of December 31, 2026.
If you did, you qualify for the larger exemption once you own a Florida home, live in it as your permanent residence, and apply for homestead.
If you did not, you start with the old structure: $25,000 for school taxes and $50,000 for non-school taxes, with the $50,000 adjusting for inflation beginning in 2028. You receive the larger exemption beginning with your fifth year of homestead exemption.
Notice what the test is. It is not when you bought your home or when you applied for homestead. It is whether you were a permanent Florida resident on December 31, 2026.
What That Difference Is Worth
Your savings come from one thing: the extra amount of value that is exempt, multiplied by your non-school tax rate. Compared with today's roughly $51,400 exemption, about $98,600 more is exempt in 2027 and about $198,600 more starting in 2028.
That gives a simple rule of thumb. Property tax rates are measured in mills, and one mill is $1 of tax for every $1,000 of taxable value. For every 1 mill of non-school tax, a homestead owner saves about $100 in 2027 and about $200 a year starting in 2028. This holds for any home assessed at $250,000 or more. You can find your non-school rate on your property tax bill or your TRIM notice.
Here is a local example. In the City of Sarasota, the certified 2025 non-school rate was about 8.8 mills. A homestead there assessed at $250,000 or more would save about $870 in 2027 and about $1,750 a year starting in 2028, assuming rates stay the same. The savings are the same whether the home is assessed at $300,000 or $3 million, because they come from the larger exemption, not the home's value.
Savings vary across the state. Florida TaxWatch's estimates range from about $350 to $1,800 in 2027, and from about $700 to $3,600 in 2028, depending on location. If your home is assessed at less than $250,000, you will save less, because you can only exempt the value you have.
Now assume you move to the City of Sarasota in early 2027 and buy a home. Your first homestead year would generally be 2028. You would receive the smaller exemption for 2028 through 2031, and the larger one starting in 2032. At about $1,750 a year, that wait could cost around $7,000.
The Three Dates That Matter
There are three dates, and each does a different job.
December 31, 2026 decides which group you are in.
January 1 of each year is when you generally must own the property and use it as your permanent residence to receive homestead for that tax year.
March 1 is the ordinary deadline to file your homestead application with the county property appraiser.
Having until March 1 to apply does not mean you can close on a house in February and receive homestead for that same year.
Buying a House Does Not Make You a Resident
This is the most common misunderstanding I'm hearing. People assume that if they close on a Florida home before December 31, they're in. That is not how it works.
Residency is a question of fact. Florida looks at where you actually live and intend to stay. Evidence includes a Florida driver's license, Florida vehicle registration, Florida voter registration, where you receive mail and file taxes, and where you actually spend your time. Many people also file a Declaration of Domicile under section 222.17 of the Florida Statutes. It is a sworn statement, filed with the clerk of court, that Florida is your permanent home.
No single document settles the question. If you close on December 15 and then return north and live there until spring, a deed and a driver's license will not make you a Florida resident on December 31.
The reverse is also true, and it matters. You do not need to own a Florida home by December 31. If you genuinely move here and rent before year end, you can be in the earlier group. When you buy later, you can qualify for the larger exemption once your homestead begins. The residency must be real and supported by the facts. Simply signing a lease does not prove it.
The same rule helps people building new homes. If your builder's closing slips from December into 2027, what matters is when you became a Florida resident, not when you closed.
Your Old State Gets a Say Too
This is the part of the conversation that is almost always missing. Florida decides whether you qualify for homestead. But the state you are leaving decides whether you have really left.
Many states, including New York, New Jersey, Massachusetts, and Minnesota, can treat you as a resident for state income tax purposes if you keep a home there and spend more than 183 days there during the year. Others focus on your domicile: where your strongest ties are. High-tax states audit people who claim to have moved to Florida, and they look closely.
Imagine someone who closes on a Florida condo, gets a Florida license, and files a Declaration of Domicile. But they keep the house up north, keep their doctors and dentist there, keep their club membership, and spend most of the year there. They may have a weak claim to Florida homestead and a strong residency audit waiting for them back home.
A real move means building ties in Florida and reducing them in the old state. Because I'm licensed in both Florida and Minnesota, I see this from both sides every week.
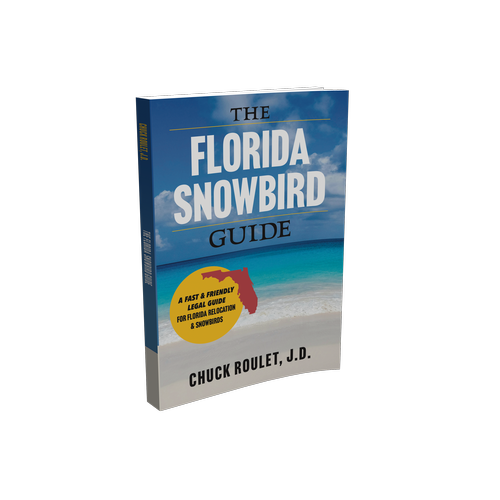
My free Florida Snowbird Guide walks you through the full process, including residency, domicile, taxes, and the estate planning changes that should come with a move. You can download it by clicking here.
The Penalties for Getting Homestead Wrong
Please don't treat December 31 as a reason to stretch the truth. Under section 196.161 of the Florida Statutes, if the property appraiser determines that someone received a homestead exemption they weren't entitled to, the appraiser can look back up to 10 years. The owner owes the unpaid taxes, a penalty of 50 percent of the unpaid taxes for each year, and 15 percent interest per year. A tax lien is recorded against the owner's Florida property. Knowingly giving false information to claim homestead is also a first-degree misdemeanor.
The smarter approach is to make a real move before December 31, or plan around the waiting period if you can't.
Titling Your Florida Home in a Trust
Many people moving to Florida want their new home in a revocable living trust, and for good reason. A properly funded trust keeps the home out of probate.
Florida law, in section 196.041, allows a home held in a qualifying revocable trust to keep its homestead exemption, as long as the trust gives you the right to live in the home. But the trust and the deed must be prepared correctly. Trusts drafted in other states often weren't written with Florida homestead in mind.
Florida homestead also carries special inheritance rules. Under Article X, Section 4 of the Florida Constitution, if you are married or have a minor child, you are limited in who you can leave your homestead to. A plan that ignores those limits may not do what you think it does.
Some people are told to use a lady bird deed instead of a trust. I explain the problems with that approach in "What a Lady Bird Deed Does — and What It Doesn't" in this article.
A move is also the time to update your other documents. Florida has its own signing requirements for powers of attorney, including two witnesses and a notary, and Florida banks and hospitals can be reluctant to accept out-of-state forms.
If You Already Live in Florida
If you are already an eligible Florida homeowner with homestead, the larger exemption begins helping you with the 2027 tax year. If you are moving from one Florida home to another, ask the property appraiser about portability. It may let you transfer part of your accumulated Save Our Homes benefit to the new home, but you must apply for it.
If you are buying a resale home, don't budget around the seller's tax bill. After a sale, the home is generally reassessed at market value the next January 1, and the seller's Save Our Homes savings don't transfer to you.
One Honest Caution
The five-year rule for new residents treats homeowners differently based on when they arrived in Florida. The U.S. Supreme Court has struck down similar residency-date tax benefits before, including in Hooper v. Bernalillo County Assessor, 472 U.S. 612 (1985). The new rule could face a legal challenge. Lawmakers and county property appraisers are also still working out how parts of Amendment 3 will be applied. Don't make a major, permanent decision based only on this tax break.
If You've Been on the Fence
People move to Florida for many reasons: taxes, weather, family, or how things are going back home. Whatever your reasons, if you've been thinking about making Florida your permanent home, Amendment 3 has turned the timing into a real decision.
Your Next Steps
First, determine when Florida became, or will become, your permanent residence. Second, make sure you are reducing your ties to your old state, not just adding ties in Florida. Third, review your trust, your deed, and your other estate planning documents for Florida law. Fourth, file for homestead by March 1 of the first year you qualify.
Click here to download the free Florida Snowbird Guide, and if you'd like help planning your move or updating your estate plan, call our Florida office at 941-909-4644 or our Minnesota office at 763-420-5087 to schedule a consultation. Or you can fill out the contact form on this page and a member of our team will reach out to you.
This article is for general information only and is not legal or tax advice. The county property appraiser makes homestead eligibility decisions. Talk with an attorney about your own situation.
About the Author
Chuck Roulet is the founding attorney of Roulet Law Firm, P.A., with offices in Minnetonka, Minnesota and Venice, Florida. He is one of very few attorneys licensed in both Minnesota and Florida, and he has nearly 30 years of experience in estate planning, elder law, and long-term care planning. Chuck has trained more than 35,000 attorneys and financial professionals and is the author of three books, including The Florida Snowbird Guide.